CAR ACCIDENT REPRESENTATION · TAMPA, FLORIDA
Medical bills, missed work, and insurance calls can make recovery feel like another full-time job. If another driver injured you, Baird Law Group can investigate the crash, explain your coverage, and pursue compensation supported by the facts.
Get guidance from a firm led by a former insurance-defense attorney. Cory A. Baird has been licensed in Florida since 2002.
Free consultation · No obligation · No fees or costs unless you recover
FLORIDA COUNSEL
Licensed in Florida since 2002
INSURANCE PERSPECTIVE
Former insurance-company defense attorney
CONTINGENCY FEE
No fees or costs unless you recover
TAMPA OFFICE
701 S. Howard Ave., Suite 201
ON THIS PAGE
UNDERSTANDING YOUR CLAIM
After a Florida car crash, more than one insurance policy may matter. PIP can cover part of certain expenses regardless of fault. A separate claim against a negligent driver may address other losses, subject to the evidence and applicable law.
Whether you were driving or riding as a passenger, we can review how the collision happened, identify potentially responsible parties, and explain the options available. A crash report is a starting point; photographs, witnesses, and medical records help build the fuller picture.
Start with what you have. You do not need a complete file to request an initial case review.
HOW BAIRD LAW GROUP HELPS
A car accident claim brings together liability, insurance coverage, and the effect of an injury on everyday life. Our work connects those pieces and gives you a clearer basis for decisions about treatment records, settlement, and possible litigation.
01
Identify video, witness information, crash photographs, and vehicle evidence before records are lost or repairs change what can be examined.
02
Analyze the traffic movement, point of impact, roadway conditions, vehicle damage, and available records to test each party’s version of the crash.
03
Handle communications with insurers and evaluate requests for statements, records, and releases while keeping you informed about the claim.
04
Review PIP, bodily-injury liability, and uninsured or underinsured motorist coverage, along with other potentially applicable policies.
05
Document treatment, time away from work, daily limitations, and supported future needs. A case should reflect the person behind the medical bills.
06
Present a supported demand, evaluate offers with you, and prepare for litigation when an appropriate settlement cannot be reached.
Different collisions raise different questions about fault, coverage, and evidence. Baird Law Group helps injured people assess claims involving:
EVIDENCE CAN MOVE FAST
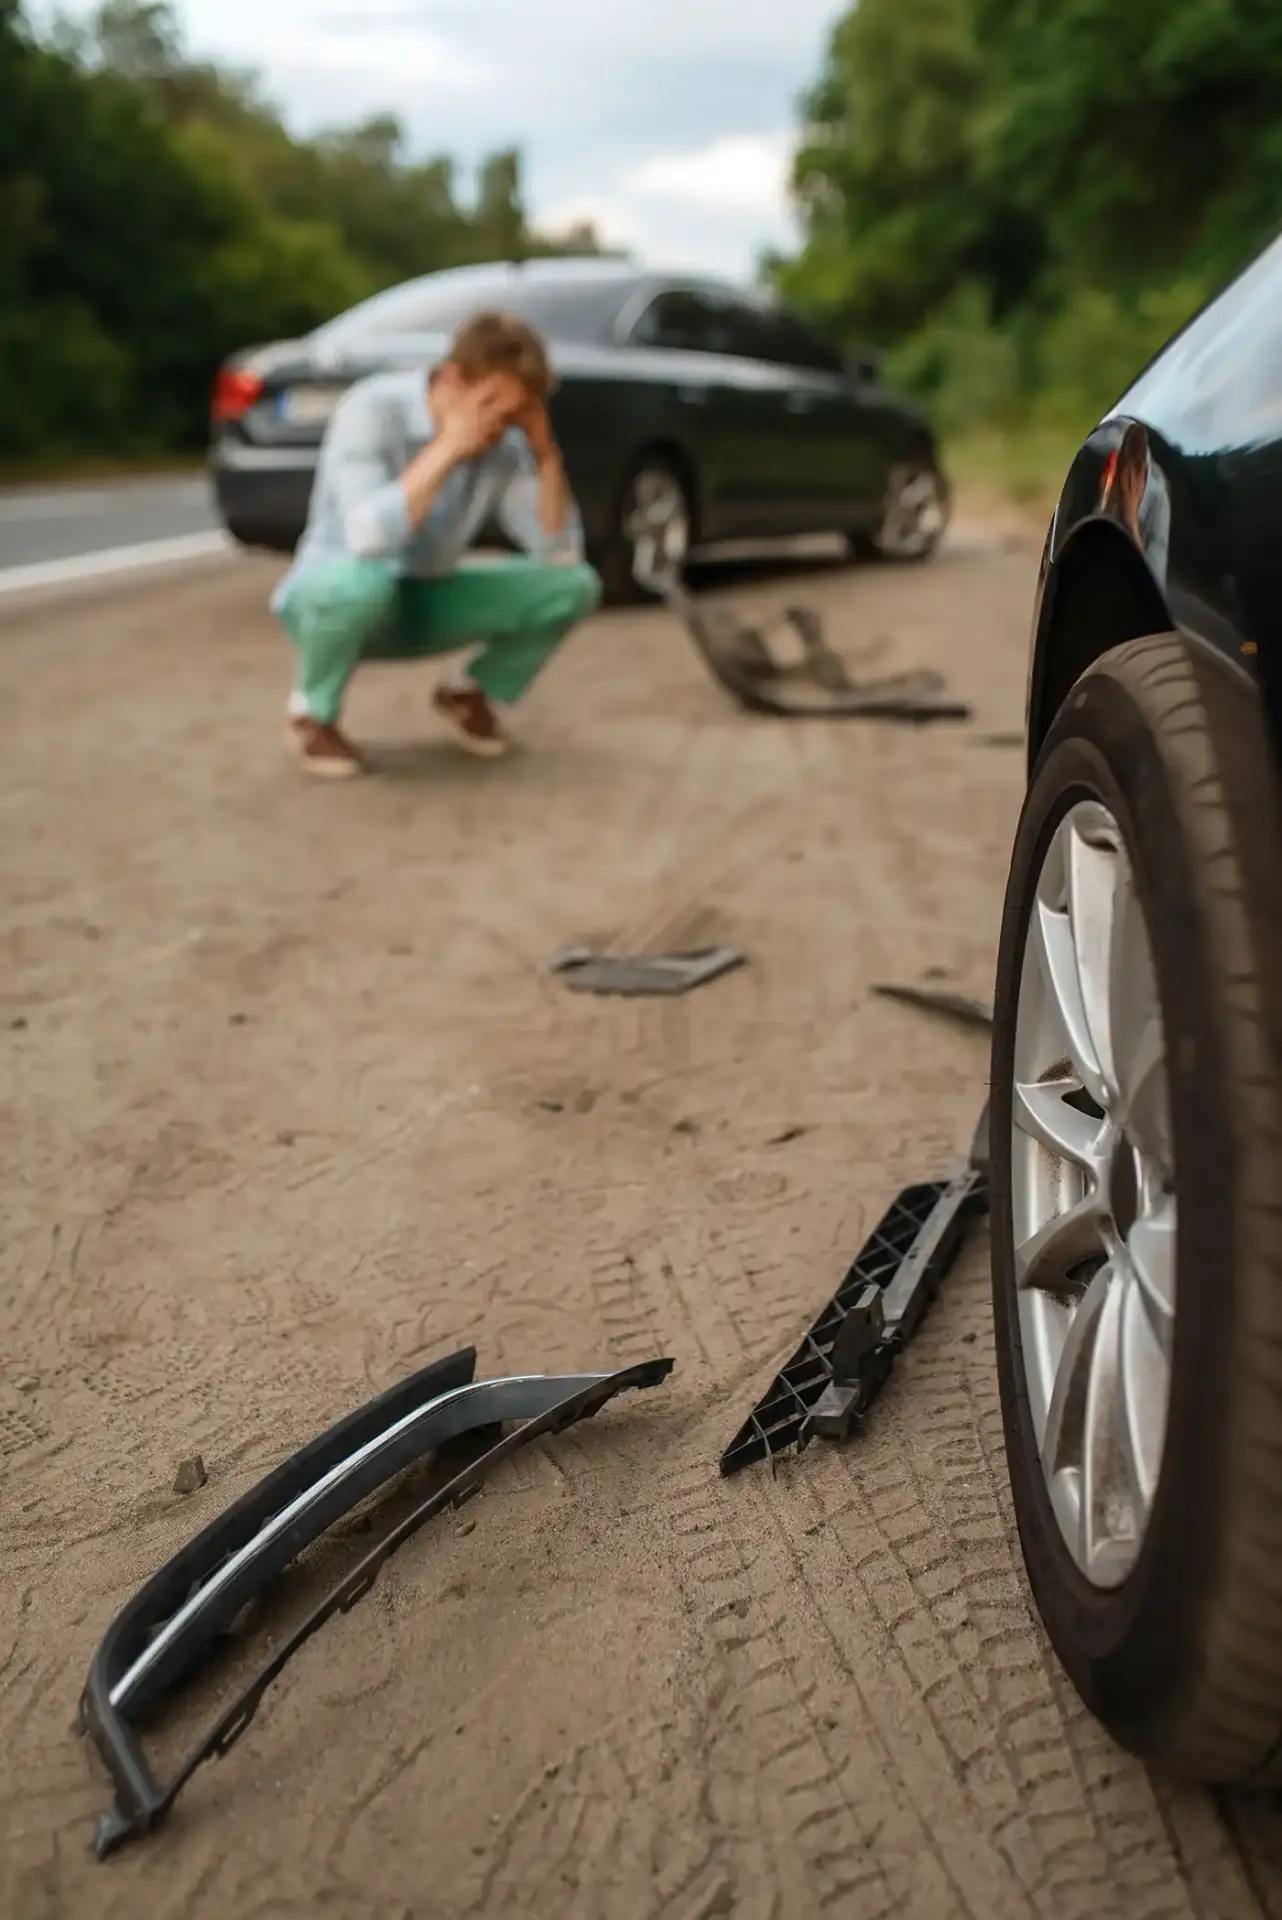
A disputed claim may turn on what happened seconds before impact. Depending on the circumstances, useful evidence can include:
Keep claim numbers, repair estimates, medical records, and missed-work documentation together. Ask for advice before discarding a damaged vehicle or authorizing repairs if it may need inspection.
MEET CORY A. BAIRD, ESQ.
Before opening his own firm, Cory Baird defended insurers in personal injury matters. That background informs his understanding of how claims are assessed and disputed.
His official biography also describes his own experience recovering from an automobile crash. At Baird Law Group, the focus is on listening to clients, explaining the process, and preparing their cases with care.
LICENSED
Florida attorney since 2002
BACKGROUND
Former insurance-defense attorney
EDUCATION
J.D. and M.B.A., Stetson University
FINANCIAL TRAINING
Former CPA; experience at Ernst & Young
AFTER A CRASH
Put safety and medical needs first. As circumstances allow, the following steps can help you preserve information and avoid preventable problems with a claim.
01
Call 911 for an emergency and seek appropriate care promptly. Tell your provider about your symptoms and when the crash occurred.
02
Contact law enforcement as required, exchange driver and insurance information, and photograph the scene only when it is safe to do so.
03
Save names and contact details for witnesses. Note nearby businesses or vehicles that may have recorded the collision.
04
Keep photos, medical paperwork, receipts, and work records. Discuss whether the vehicle needs inspection before repair or disposal.
05
Notify your own insurer as your policy requires. Get advice before giving another driver’s insurer a recorded statement or signing a settlement release.
06
Ask about the deadlines and coverage that apply to your facts. Follow your treatment plan and tell your provider if symptoms change.
FLORIDA LAW
The rules below address different parts of a claim. The crash date, insurance terms, and type of defendant can change the analysis. A case review should establish the deadlines that apply to you.
For covered injuries, Florida PIP generally pays 80% of reasonable, necessary medical expenses and 60% of qualifying lost income, subject to a combined $10,000 limit, deductibles, and other restrictions. Initial qualifying care must be received within 14 days. Medical benefits may be limited to $2,500 depending on the emergency-medical-condition determination.
In negligence actions governed by Florida’s modified comparative-fault rule, damages are reduced by your share of fault. A person found more than 50% responsible for their own harm cannot recover damages under that rule. Disputed fault deserves careful investigation.
Florida generally allows two years for a negligence action. The 2023 change to this period applies to claims accruing after March 24, 2023. Exceptions, government claims, and other types of actions can involve different deadlines or notice requirements. Do not assume settlement discussions stop the clock.
When Florida’s motor-vehicle tort threshold applies, noneconomic damages generally require a qualifying injury: significant permanent loss of an important bodily function, permanent injury within a reasonable degree of medical probability, significant permanent scarring or disfigurement, or death. Medical evidence matters; not every injury meets the threshold.
COMPENSATION
There is no reliable settlement number without reviewing the facts. Available damages depend on responsibility, injury evidence, insurance, and applicable law. Depending on the claim, recoverable losses may include:
UNINSURED / UNDERINSURED DRIVERS
UM/UIM coverage may help with covered bodily-injury losses caused by an uninsured or underinsured driver. Coverage is not automatic: the policies, any rejection or limits selection, and the crash facts need review.
Neck and back injuries, fractures, traumatic brain injuries, and spinal cord damage can affect work, mobility, and independence. The medical record should explain both the injury and its practical effects.
Supported future care, rehabilitation, assistance, and reduced earning capacity should be evaluated before a claim is resolved. These losses require evidence; they are not automatic additions to a settlement.
We can explain how an offer compares with the documented losses, available coverage, and risks of the case. Signing a release may end the right to seek additional payment for the released claims.
LOCAL REPRESENTATION · TAMPA
From our office at 701 S. Howard Ave., Suite 201, Tampa, Baird Law Group helps injured people navigate medical records, insurance questions, and the disruption a crash leaves behind.
Our approach combines an investigation of the facts with clear explanations of your options. Learn more about our firm or explore our practice areas.
FREQUENTLY ASKED QUESTIONS
Answers to common questions about claims, insurance, and hiring a lawyer.
The initial case evaluation is free. Baird Law Group handles personal injury matters on a contingency-fee basis: no attorney’s fees or costs unless you recover. The written fee agreement explains the terms that apply to your representation.
Initial qualifying medical care must be received within 14 days after the crash for PIP medical benefits. This is different from the lawsuit deadline. Missing the PIP requirement does not, by itself, determine every other potential claim.
Most Florida negligence claims accruing after March 24, 2023, have a two-year filing period. Exceptions and different causes of action can change the analysis. Get the deadline checked for your facts rather than relying on an insurer’s settlement timeline.
Potentially. For a claim governed by Florida’s modified comparative-fault rule, your recovery is reduced by your percentage of responsibility. More than 50% fault for your own harm bars recovery under that rule.
A meaningful estimate requires evidence of fault, the injuries and treatment, income losses, future needs, and available insurance. There is no dependable formula based only on the type of collision or a multiple of medical bills.
Your own or another applicable UM policy may provide coverage, depending on the policy and facts. Preserve any identifying information, report the crash, and promptly review notice and claim requirements. Coverage cannot be assumed.
An injured passenger may have a claim against a driver or another responsible party. Which PIP and liability policies apply depends on the circumstances. A lawyer can review the drivers, vehicles, and available coverage.
Your own insurer may have policy-based cooperation requirements. Another driver’s carrier has a different role. Understand who is asking and get advice about your obligations before a recorded statement or broad medical authorization.
Timing depends on the medical picture, disputes about responsibility, available coverage, and whether a lawsuit becomes necessary. An early offer may arrive before future needs are clear. We can discuss the next steps without promising a resolution date.
Some claims resolve through negotiation; others require a lawsuit or trial. We evaluate settlement opportunities and litigation with you based on the evidence and circumstances. No specific outcome can be guaranteed.
START WITH A CONVERSATION
Tell us when the crash happened, what injuries you are dealing with, and what you need help understanding. We can review the next steps and explain whether the firm can help.
Prefer to speak by phone?
Call 813-849-2679
FREE CASE EVALUATION
Complete the form below and a member of Baird Law Group will contact you.
Please share only a brief summary. Do not include Social Security numbers or other highly sensitive information. Sending this form does not create an attorney-client relationship or mean that the firm has accepted your case. Privacy Policy.
Legal information: This page provides general information, not legal advice. The facts and applicable law determine the options in a particular case. Past results do not guarantee future outcomes.
Florida law referenced: PIP benefits (§ 627.736) · Motor-vehicle injury threshold (§ 627.737) · Comparative fault (§ 768.81) · Filing periods (§ 95.11) · UM coverage (§ 627.727).